IRS Form 843: When to Use It, How to File, and What Happens Next
IRS Form 843 looks simple, but it can be the wrong form for the tax issue you need to fix. The real work is deciding whether you want the IRS to return an eligible amount already paid, remove an eligible charge still assessed, or correct a return through another form.
The clock matters here. A refund claim and an unpaid abatement request are not the same, and the date printed on an IRS notice may control what you should do next.
Before completing Formulario 843 del IRS, identify the charge, tax period, payment status, and notice deadline. Those details determine the form, evidence, and filing address. Start with the quick answer below, then confirm your route before filling in any lines.
Respuesta rápida y puntos clave
Respuesta rápida: IRS Form 843 is used to claim a refund or request an abatement of certain taxes, penalties, interest, fees, and additions to tax. Under the Instrucciones del IRS, it does not amend an income tax return, and your notice may give you a more direct response route. First identify whether the amount is paid or unpaid, then check the deadline, evidence, and filing address.
Puntos clave
- Read the notice before using the form.
- Verify charges in your Cuenta en línea del IRS.
- Do not use it to change Form 1040 income or credits.
- Paid refunds and unpaid abatements follow different rules.
- Prepare one form for each tax period.
- Explain the amount and attach proof.
- Keep the signed form and delivery evidence.
What is IRS Form 843?
IRS Form 843 is the form for certain refunds and abatements involving paid amounts or unpaid charges. Claim for Refund and Request for Abatement is its title. It only covers specified taxes, penalties, interest, fees, and additions to tax. It is not the general form for correcting an income tax return, so the charge, payment status, tax period, and reason for relief determine whether it fits.
Refund claim versus abatement request
The distinction is practical. If the IRS already collected an eligible penalty, you are seeking a refund; if the penalty remains on the account and qualifies for relief, you are requesting abatement before payment. The underlying tax is separate from any penalty or interest added to it, as the IRS instructions explain.
| Solicitud | Significado |
|---|---|
| Reembolso | Return an eligible amount already paid. |
| Abatement | Reduce or remove an eligible assessed amount. |
When should you use IRS Form 843?
Use IRS Form 843 only when your refund or abatement request matches the allowed uses and a reason box on the current form.
Penalties and additions to tax
A penalty claim requires motivo justificado or another lawful ground. Erroneous written IRS advice may support relief from certain penalties. Trust Fund Recovery Penalty claims are specialized and high-risk, so they need individual review.
Interest and other eligible charges
El interest abatement test is narrow. Section 6404(e)(1) generally requires an unreasonable ministerial or managerial IRS error or delay. Other limited uses include a zero net interest rate, specified fees, and qualifying claims.
Employee withholding claims
An employee may claim excess or erroneous Social Security, Medicare, or RRTA tax withheld by one employer when that employer will not correct the overcollection. Certain excess tier 2 RRTA claims also fit. Employers must use an employment-tax correction form.
| Situación | Form 843? | Condition to check | Best first action |
|---|---|---|---|
| Penalización | Quizás | Valid relief ground | Check the notice and penalty code |
| Intereses del IRS | Quizás | Section 6404(e)(1) | Record the error and relevant dates |
| Employee withholding | Quizás | Employer will not adjust | Ask the employer to correct it |
When should you not use IRS Form 843?
Do not use IRS Form 843 when the IRS requires an amended return, an employment-tax correction form, or another specific claim form.
The IRS instructions may require another form:
Lo que no significa
| Mistaken assumption | Correct direction |
|---|---|
| It amends Form 1040 income, deductions, credits, filing status, or tax. | Use Form 1040-X when its rules apply. |
| It generally refunds underlying income tax or Additional Medicare Tax. | Use the return-specific correction or claim process. |
| An employer can use it to correct FICA, RRTA, or income-tax withholding. | Use the corresponding employment-tax form, such as Form 941-X when applicable. |
| It recovers an injured spouse’s share of a joint refund offset. | Review Form 8379. |
| It is the general fuel or excise refund form. | Review Form 4136, Form 8849, or Form 720-X as applicable. |
| Filing it automatically pauses collection or another notice deadline. | Continue following the notice unless the IRS confirms otherwise. |
| It is a general hardship request. | Match the charge to an actual legal or administrative relief ground. |
Should you call the IRS before filing Form 843?
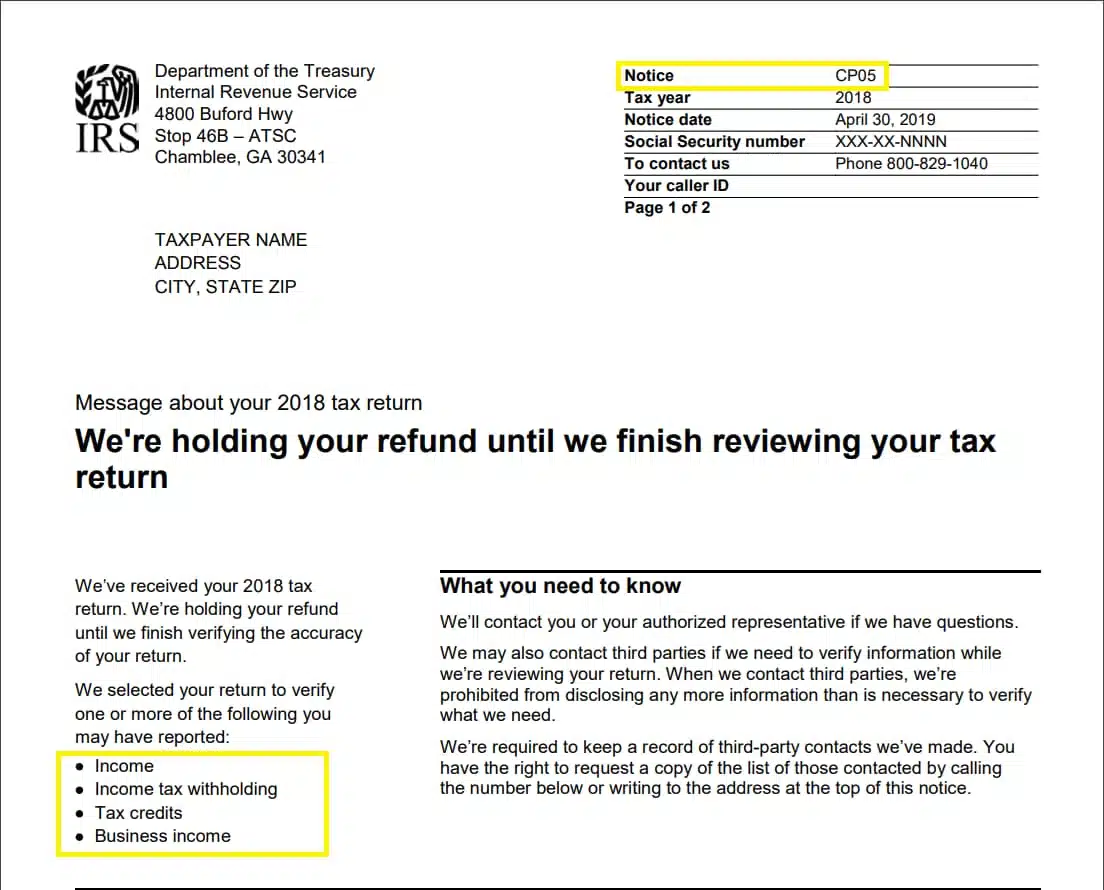
Often, yes, because your notice instructions may let you llamar al IRS for certain penalty relief or respond directly without filing IRS Form 843.
Check AEP before requesting FTA
September 2026 update: El exención de sanciones administrativas rules changed that summer when Automatic Exemption from Penalty began. AEP starts with eligible original 2025 tax-year returns and 2026 quarterly returns, then carries forward. If compliance-history requirements are met, it automatically applies to specified failure-to-file, failure-to-pay, and failure-to-deposit penalties.
Relief follows processing of the original return; the IRS sends a letter, so you do not request it. First Time Abate (FTA) remains available for earlier periods and eligible 2025 or 2026 cases not considered for AEP; you must contact the IRS. Contact the IRS when an assessed penalty should receive AEP.
Before-you-call checklist
- Notice/letter and response date.
- Form and tax period.
- Penalty, amount, and IRC section shown.
- Payment dates and status.
- Transcript or online account record.
- Timeline and supporting documents.
How do you fill out IRS Form 843?
Utilice el current IRS Form 843, revised December 2024; choose one reason box at the top, then complete Lines 1 through 8 for the correct period and amount.
| Part | What to enter | Mistake to avoid |
|---|---|---|
| Top reason box | One filing reason | Checking multiple boxes |
| Name, TIN, address | Claimant details matching the claim | Inconsistent names or identification numbers |
| Línea 1 | Beginning and ending dates for one tax period or fee year | Combining unrelated periods |
| Line 2 | Exact amount requested | Omitting the computation |
| Line 3 | Payment dates for a refund claim | Using assessment dates instead |
| Línea 4 | Related tax or fee type | Checking several boxes without an allowed exception |
| Línea 5 | Related return or fee | Selecting an item that conflicts with the notice |
| Line 6 | Penalty’s IRC section | Guessing instead of checking the notice or records |
| Line 7 | Reason category | Treating the box as the full explanation |
| Line 8 | Facts, legal or administrative basis, and amount computation | Giving vague conclusions without dates or proof |
| Signature | Required taxpayer, spouse, officer, fiduciary, or preparer signature | Missing a joint-return spouse’s signature or officer title |
Generally, prepare a separate IRS Form 843 for each tax period, fee year, and type of tax unless the form instructions allow a narrow exception. An authorized representative may file, but Form 2848 must be attached as instructed.
What evidence should you attach to Form 843?
Attach records proving the basis and calculation on IRS Form 843.
Build the Line 8 explanation
- State the exact relief and amount.
- Identify the notice, penalty or charge, and period.
- List events by date.
- Tie the facts to the relief ground.
- Para motivo justificado, describe ordinary care, the obstacle, and correction date.
- Show the amount calculation.
- Label attachments and keep a complete copy.
Match documents to the claim
Uso documentos justificativos that fit the claim:
- Causa razonable: Dated medical, disaster, court, system, or record-access evidence showing the event and duration.
- Erroneous written IRS advice: Your written request, the IRS response, and assessment notice.
- Employee withholding: Employer statement or an explanation of why it was unavailable, Form W-2, and claim-specific records.
- Interest abatement: IRS contacts, delay timeline, taxpayer responses, and a calculation limited to the disputed period.
- Representative filing: Form 2848.
If the notice, dates, or periods conflict with your transcripción fiscal, request a tax resolution review before filing.
When and where do you file Form 843?
File IRS Form 843 by its deadline, using the notice or current instructions.
Which deadline applies?
IRS Form 843 has no fixed processing time; filing and response deadlines differ.
| Situación | Timing | Next action |
|---|---|---|
| Aviso | Printed date controls | Calendar it; follow instructions |
| Paid refund | Refund deadline: later of 3 years from original filing or 2 from payment; limits and exceptions apply | Verify dates |
| Unpaid abatement | Paid-refund timing may differ | Consulte el refund or abatement route |
| Section 6404(e)(1) interest | Interest abatement: three years from filing or two years from payment, whichever is later | Build the IRS-delay timeline |
| Mailed | No fixed estimate | Keep proof; monitor mail/account |
| Penalty rejection | Usually 30 days from letter | Follow the letter |
| Disallowance | Two-year court period | Seek legal review |
| Six months | Suit timing, not processing | Get legal advice |
Use filing, payment, and notice dates to calculate a deadline.
Where should it go?
Use the notice address. Otherwise follow the instrucciones de presentación, often the service center for the related current-year return. No universal address applies. Keep signed form, attachments, and delivery proof.
Can it be filed electronically?
Most claims are mailed. A narrow electronic option exists for certain IRS Online Account users filing fully paid penalty or interest claims citing Kwong v. United States. Verify eligibility and deadline; it is not general e-filing.
What happens after you file Form 843?
The IRS may allow, partly allow, deny, or request more information about your IRS Form 843 claim. Its estado del procesamiento page gives no fixed Form 843-specific estimate.
Monitor the claim without guessing a date
Keep delivery proof and complete filing package. Watch IRS mail and compare account adjustments with the amount requested. Use your online account or transcript as a check, not a real-time tracker. Penalty-related interest generally adjusts automatically when the IRS reduces or removes an eligible penalty.
Act on the letter you receive
A penalty-relief rejection generally allows 30 days to request review under the appeal deadline; the letter controls. A refund disallowance starts a separate two-year court period, and administrative reconsideration or Appeals does not automatically stop it.
En virtud de la claim timing rules, six months without action on a formal refund claim can affect when a refund suit may be filed. That is not an expected processing time. Consult qualified counsel before any court step.
Common Form 843 filing mistakes
Before mailing IRS Form 843, correct these errors:
- Check the notice first; it may offer a direct response route.
- Do not use this claim process to amend income tax; use the return-specific form.
- Separate tax periods and unrelated claim types.
- On the current form, select one top reason box.
- Do not copy an old mailing address; verify the instrucciones de presentación.
- Line 8 needs specific facts and an amount calculation.
- Attach applicable evidence, Form 2848, an employer statement, Form W-2, and required signatures.
- A commercial processing estimate is not a deadline or IRS promise.
Before you mail:
- Current form.
- Correct claim.
- One period.
- Exact amount.
- Relevant dates.
- Supporting proof.
- Signatures and complete copy.
When is professional help worth considering?
Professional help with IRS Form 843 is worth considering when a claim involves personal liability, multiple periods, disputed records, narrow interest rules, a denial, or an uncertain deadline.
DIY may be reasonable when:
- One notice, period, and clearly identified penalty.
- Clear amount and relief ground.
- Organized supporting documents.
- No active appeal, disallowance, or court deadline.
Consider prompt review when:
- Trust Fund Recovery Penalty, payroll tax, responsible-person exposure, or multiple periods or entities.
- IRS error or delay, erroneous written advice, or a disputed computation.
- Account, return, notice, and transcript conflict.
- Denial or approaching legal deadline.
H&S Accounting & Tax Services ofrece IRS notice and transcript reviews, penalty abatement requests when appropriate, and IRS correspondence when authorized.
IRS Form 843 FAQs
What is IRS Form 843 used for?
Form 843 may fit certain refund or abatement requests. Examples include certain penalties, interest charges, and excess employee Social Security or Medicare withholding. The Instrucciones del IRS make one limit clear: it does not correct a previously filed income tax return.
What is a good reasonable cause for IRS penalty abatement?
Bien motivo justificado shows that you exercised ordinary care but could not comply. Serious illness, a disaster, unavailable records, or system problems may support the facts. No example guarantees relief; the IRS evaluates the circumstances and timing case by case.
How long does the IRS take to respond to Form 843?
No standard response period appears for Form 843 on the IRS estado del procesamiento page. Save delivery proof and your copy, then watch mail and account records. If a letter arrives, its stated response date matters more than a commercial estimate.
How do you get first-time penalty relief in 2026?
Eligible AEP applies automatically to covered starting periods, while First Time Abate remains request-based for earlier periods or eligible cases not considered for AEP. Read your notice and compare the current exención de sanciones administrativas rules before contacting the IRS directly.
Can Form 843 be filed electronically?
Generally, no. The electronic option is narrow and applies to certain individuals using an IRS Online Account for fully paid penalty or interest claims citing Kwong v. United States. Two details control online filing here: the claim and its deadline.
What is the deadline for filing Form 843?
Deadlines vary by claim. Paid refunds generally follow the refund deadline: the later of three years after original filing or two years after payment. An unpaid refund or abatement request is different, and a notice may set a response date.
Final takeaway on IRS Form 843
Start by naming the issue correctly. Are you asking for money already paid, removal of an eligible assessed charge, or a correction that belongs on another form? That choice sets the filing route.
Next, read the current notice and instructions before calculating the deadline or choosing a mailing address. Your explanation should identify the amount, tax period, dated facts, relief basis, and calculation. Match each statement to supporting records, and save a signed copy with delivery evidence.
For a complex claim or tight deadline, concertar una cita with H&S Accounting & Tax Services, a CPA-led practice based in Hollywood, Florida that provides remote IRS notice and tax-resolution reviews nationwide.