LLC to S Corp: How the tax election works and what changes
If you already own an LLC, switching from LLC to S Corp usually means changing its federal tax treatment, not shutting it down and forming a corporation. Your business may remain an LLC under state law even though its LLC tax classification changes with the IRS.
That election changes how you pay yourself and how business income appears on your federal tax returns. Potential employment-tax savings can be appealing, but weigh them against a reasonable owner salary, payroll filings, bookkeeping, a separate business return, and ongoing costs. A lower tax bill is not automatic.
Before filing, you may want your tax and accounting setup reviewed. Our business formation services include that review. This guide explains how to make the election and how to decide whether it makes sense for your LLC.
Quick answer and key takeaways
Quick answer: An eligible LLC can elect S corporation tax treatment by filing Form 2553. You generally do not need to form a new corporation under state law. An LLC to S Corp election may reduce employment taxes by separating reasonable wages from other income and distributions. Payroll and the annual S corporation return cost money, and those costs can erase the savings.
Key takeaways
- Your LLC can remain the same legal entity.
- Form 2553 makes the federal S corporation election.
- No profit threshold guarantees savings.
- Working owners generally need reasonable wages.
- Payroll and Form 1120-S add recurring costs.
- Missed the filing window? Check whether late-election relief applies.
- Put the expected savings next to your yearly payroll and filing costs.
What does LLC to S Corp actually mean?
LLC to S Corp means your existing limited liability company elects S corporation treatment for federal tax purposes. An LLC is formed under state law, while its LLC taxation depends on federal classification rules. The election generally changes how the IRS taxes the business without changing its state-law form.
Without an election, a single-member LLC is generally treated as part of its owner’s income tax return. If you own it alone, business income commonly goes on Schedule C. A multi-member LLC generally defaults to partnership taxation and files a partnership return, with income reported to its members.
If your LLC qualifies, you can request S corporation treatment through Form 2553. A valid LLC to S Corp election generally establishes corporate classification for federal tax purposes, so a separate Form 8832 is usually unnecessary. Check your state’s requirements separately; the federal election does not make state rules uniform.
Can switching an LLC to S Corp reduce taxes?
An LLC to S Corp election can reduce employment taxes in some cases, but the result depends on what you earn and what counts as reasonable pay for your work. Without the election, a single-member LLC owner’s business profit may be subject to self-employment tax, even when the owner leaves cash in the business.
After the election, a shareholder who works for the company generally must receive reasonable wages before taking nonwage distributions. The IRS explains this reasonable compensation requirement. Our S Corp payroll guide covers salary and payroll filings. Wages carry payroll taxes; nonwage distributions generally do not. There is no fixed IRS salary percentage you can use to shift most of your pay into distributions.
| Money category | What it represents | Federal tax treatment | What the owner should check |
|---|---|---|---|
| W-2 salary | Pay for your work | Subject to payroll taxes and income tax | Is the wage reasonable for your duties? |
| Pass-through income | Your share of business profit | Generally included in your taxable income, even if undistributed | Does your Schedule K-1 reflect the profit? |
| Distribution | Cash or property paid to you as an owner | Generally no employment tax; income tax depends partly on shareholder basis and other facts | Do your basis records support the distribution? |
What does an LLC to S Corp election cost?
Form 2553 is only the filing step. An LLC to S Corp election may involve professional preparation or review, payroll setup and processing, employer payroll taxes, deposits, and payroll returns.
You also need books that distinguish wages from owner distributions and reconcile the related accounts. That is recurring work; our accounting services cover reconciliation and financial reporting when included in the engagement.
| Cost | One-time or recurring? | Why it matters |
|---|---|---|
| Election setup or review | Usually one-time | Professional help may add a fee. |
| Payroll setup | Usually one-time | Wage payments need a working payroll system. |
| Payroll processing | Recurring | Paychecks, deposits, and returns take ongoing work. |
| Employer payroll taxes | Recurring | Reasonable wages create an employer tax cost. |
| Bookkeeping and reconciliation | Recurring | Records must separate pay, profit, and distributions. |
| Form 1120-S preparation | Annual | The return includes Schedule K-1 for shareholders. |
| State-specific requirements | Varies | Fees, registrations, or taxes may apply. |
Correcting mishandled payroll or an election can add costs. No universal profit threshold guarantees savings. Compare total employment taxes under both treatments using a supportable salary. Then weigh the difference against the added payroll, bookkeeping, filing, and state costs.
Does your LLC qualify for S Corp status?
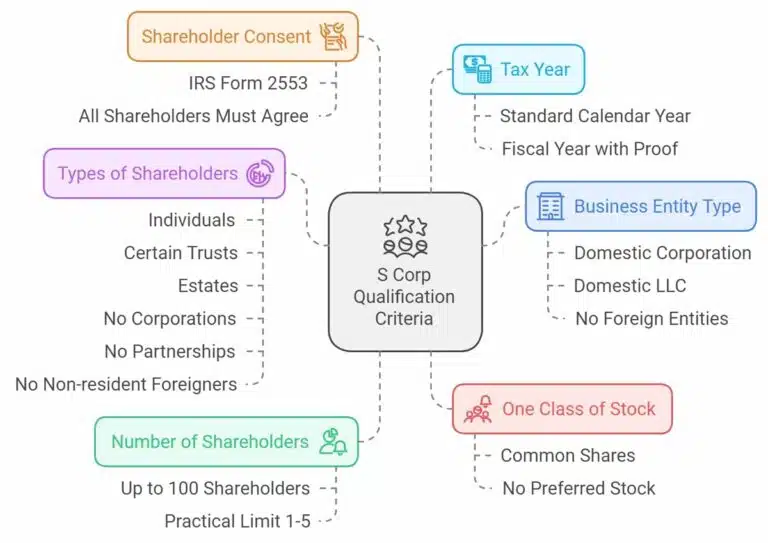
Before requesting an LLC to S Corp election, check the owners as well as the business. A domestic LLC can qualify if its ownership and tax structure meet the S corporation rules.
Confirm these before filing:
- Is the LLC domestic and otherwise eligible?
- Will it have no more than 100 shareholders?
- Are all owners permitted shareholders, such as individuals, estates, certain trusts, or exempt organizations? Nonresident aliens cannot be shareholders.
- Do owners have identical rights to distributions and liquidation proceeds? Different voting rights alone do not create a second class of stock.
- Is the entity outside the excluded categories: certain banks using the reserve method for bad debts, insurance companies, and current or former domestic international sales corporations?
- Have all shareholders whose consent is required signed the election?
The IRS S corporation eligibility instructions identify who may own shares and whose consent is needed. If one member is an ineligible shareholder, the LLC to S Corp election cannot take effect as requested.
How do you switch an LLC to S Corp?
An LLC to S Corp election uses Form 2553. First, find out how the IRS taxes your LLC now and choose when you want S corporation treatment to start.
- Start with the LLC’s federal tax classification. Is it disregarded, taxed as a partnership, or taxed as a corporation?
- Before preparing the form, look at the LLC’s owners under the S corporation rules. An owner who cannot hold S corporation stock can stop the election.
- Choose the tax year and intended effective date. Your payroll setup and first S corporation return need to follow the accepted date.
- Each shareholder who must consent needs to sign Form 2553 before you file.
- Use the current Form 2553 instructions to complete the form, paying close attention to the effective date and signatures. An eligible LLC that validly elects S corporation treatment generally has no separate Form 8832 to file.
- File using a method the current instructions allow, and save proof of filing. Do not rely on an old mailing address or fax number.
- Watch for a notice from the IRS. Check whether it accepts the election and what effective date it gives. Sending the form alone proves neither.
- Once accepted, put payroll, bookkeeping, and S corporation return preparation in place for that date. The LLC to S Corp election changes the federal filing work from then on.
When is Form 2553 due, and what if you missed it?
For an LLC to S Corp election, Form 2553 is generally due within two months and 15 days after the tax year begins. An existing entity can also file during the preceding tax year. If its year begins January 1, March 15 is the usual current-year election deadline. A different tax-year start changes the calculation.
Missed it? Late election relief under Rev. Proc. 2013-30 may apply, generally within three years and 75 days of the intended effective date. The LLC must meet the conditions, including reasonable cause and consistent tax reporting; filing late alone does not secure relief.
| Situation | What timing to expect | What to do |
|---|---|---|
| Election for a future tax year | During the preceding tax year, if one exists | Choose the effective date. |
| Election for a current calendar year | March 15 is common for an existing entity | Check the tax-year start. |
| Deadline missed | Relief may be available | Check eligibility before filing late. |
| Filed, but no IRS notice | A decision generally arrives within 60 days | Follow up after two months in an ordinary case. |
What changes after the S Corp election takes effect?
Once an LLC to S Corp election takes effect, an owner who works in the business generally needs to be paid as an employee. The IRS explains how this applies to shareholder-employees. Regular owner payroll follows: calculate a reasonable salary, document how you arrived at it, withhold federal income tax when required, and make employment-tax deposits and returns. Our payroll services can cover processing and specified filings when those tasks are included in the engagement. Wages go on Form W-2.
For each effective S corporation tax year, the business generally files Form 1120-S. Its Schedule K-1 reports each shareholder’s share of income, deductions, and other tax items. Our tax preparation services can cover business and individual returns when included in the agreed scope. Passing income through to your personal return does not mean payroll withholding will cover the whole income-tax bill; you may still need estimated payments.
Keep wages, pass-through income, and owner distributions in separate accounts. If the books treat every transfer to you as payroll or every withdrawal as a distribution, Form W-2, Schedule K-1, and your records may no longer agree. Reconcile those accounts throughout the year so the LLC to S Corp election is reflected in the actual filings.
What does LLC to S Corp not automatically mean?
The IRS election changes tax reporting; payroll and acceptance require separate attention.
| It does not automatically mean... | What is actually true |
|---|---|
| You formed a new state-law corporation | Your LLC may remain the same legal entity under state law. |
| All business profit becomes tax-free | S corporation income generally passes through to shareholders for income tax. |
| Distributions can replace salary | A working shareholder generally needs reasonable compensation for services. |
| There is an IRS-approved 60/40 salary rule | Pay depends on the work and circumstances, not a fixed percentage. |
| Every profitable LLC should elect | Payroll, bookkeeping, and return costs can exceed projected tax savings. |
| An existing LLC needs a new EIN solely because it changed its tax election | An existing LLC generally keeps its EIN when it elects S corporation taxation. |
| Filing Form 2553 proves the election was accepted | Wait for the IRS determination and verify its effective date. |
When should you get professional help with an S Corp election?
If an LLC to S Corp election only saves tax with an unusually low owner salary, review the numbers. Profit close to a supportable salary may leave little after payroll costs. Multiple owners also call for a closer look, particularly if one may be ineligible to hold S corporation stock.
Get help if you missed the Form 2553 deadline, took distributions without setting up payroll, or still have no payroll system. Prior returns showing inconsistent entity classifications need review. So do books that mix wages, distributions, contributions, and other owner transactions. An unclear effective date or missing IRS acceptance notice leaves return treatment uncertain.
Before filing or continuing, review expected savings, ownership, effective date, payroll setup, and records together.
Frequently asked questions
Can a single-member LLC elect S Corp status?
Yes. An LLC to S Corp election is available if the single-member LLC and its owner meet federal requirements. Having one owner does not prevent the election. The IRS describes the S corporation election available to eligible LLCs.
Do I need a new EIN when switching to S Corp taxation?
An existing LLC generally keeps its EIN when changing a tax election. A new single-member LLC that previously needed no EIN may need one when electing corporate or S corporation taxation. Check the LLC EIN rules.
Do I need Form 8832 before Form 2553?
Usually not. A valid S election by an eligible LLC also establishes corporate classification for federal tax purposes. You generally can file Form 2553 without filing Form 8832 first. See the Form 2553 rules.
How much profit should an LLC make before electing S Corp status?
There is no universal IRS profit threshold. Compare self-employment tax under the LLC’s current treatment with both sides of payroll tax on reasonable S corporation wages. Then account for payroll processing, bookkeeping, Form 1120-S preparation, and applicable state costs. Profit alone does not settle the calculation.
Can I take distributions instead of paying myself a salary?
Generally, no, if you work for the company and receive or have the right to receive payment. Distributions cannot replace reasonable wages, though every dollar of profit need not be salary. See the IRS guidance on shareholder wages.
What happens if I file Form 2553 late?
A late LLC to S Corp election may qualify for relief if the entity was eligible, had reasonable cause, and reported income consistently with the intended election. Approval is not automatic. Check the late S corporation election requirements.
Check the numbers before you make the election
Start with the LLC’s current federal tax classification and whether every owner qualifies for S corporation ownership. Then estimate a reasonable salary for the work you perform. Use that salary to calculate the employment-tax difference.
An LLC to S Corp election brings employer payroll taxes, payroll processing, bookkeeping, Form 1120-S preparation, and other recurring costs. Include the employer payroll tax in your tax comparison, then subtract the additional operating costs from the projected savings.
Choose the intended effective tax year and check the Form 2553 deadline. Can payroll and the books be ready by that date? Keep proof of filing, then check the IRS notice for acceptance and the effective date before preparing returns under the new classification. If the election only works with an unrealistically low salary or missing expenses, do the calculation again before filing.