IRS Form 1096: Who Must File? Steps, Rules, and Deadlines
Before you mail your business’s 1099s, check whether your filing needs a separate summary sheet. You’ll use Form 1096 to send certain paper returns to the IRS, but it doesn’t belong with an electronic submission. The IRS explanation identifies the paper returns it covers.
That distinction comes before filling in any boxes. The transmittal summarizes a paper submission. You won’t necessarily need that summary just because your business issues 1099s. Whether you’re allowed to file on paper determines that answer.
Start below with the filing requirements and how to obtain the paper copy. Once you’ve confirmed that you need it, the box instructions explain which figures to carry over from your returns, followed by the deadlines and directions for mailing them to the IRS.
Quick answer and key takeaways
Quick answer: Use Form 1096 when you send designated information returns to the IRS on paper. You don’t need this summary form when you e-file. Before choosing paper, count your returns. Filing ten or more combined generally requires electronic filing unless you qualify for a waiver or exception under the IRS e-filing rules. Identify the return types before ordering forms.
Key takeaways
- Count W-2s with your other information returns when testing the threshold.
- Give paper 1099-NEC returns their own transmittal, separate from 1099-MISC.
- Order the official scannable form. The downloadable informational PDF won’t work for filing.
- Find your deadline in that return’s instructions.
- Summary figures should match attached returns: counts, federal withholding, and form-specific dollar amounts.
What is Form 1096?
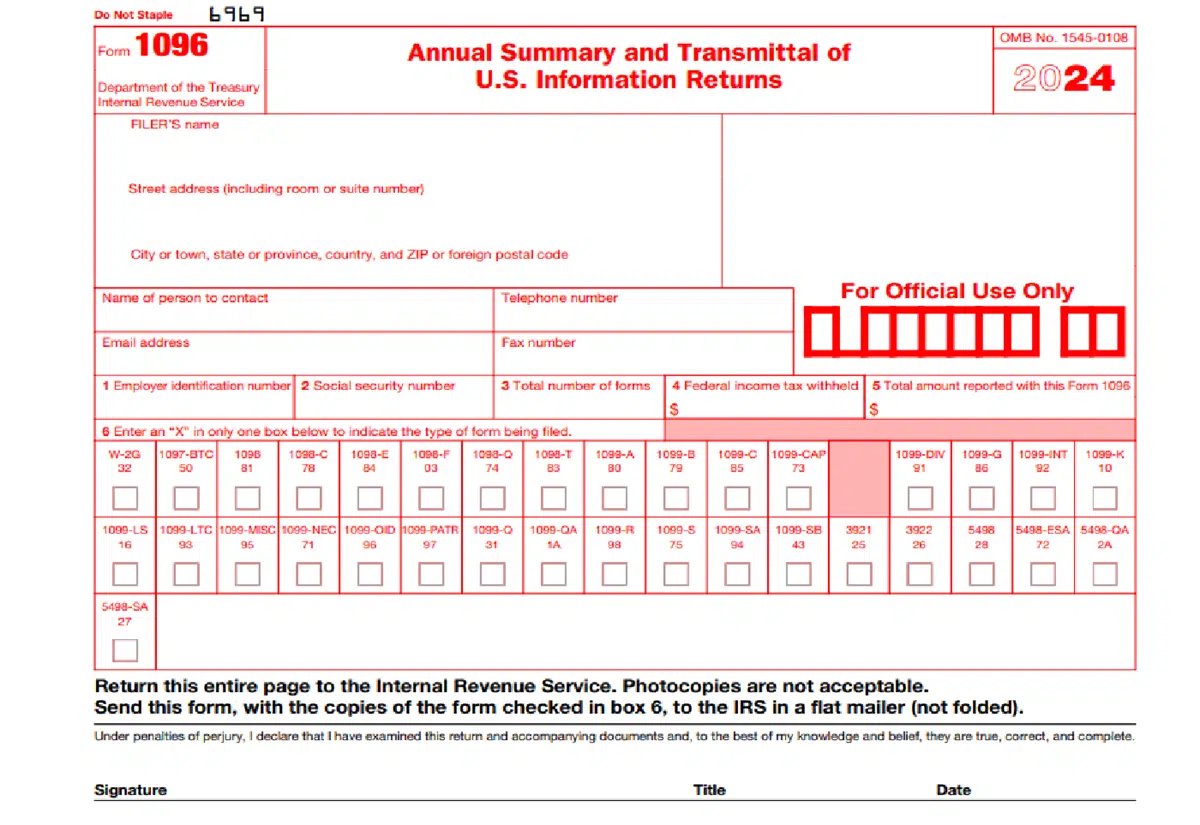
It’s the summary you file with a batch of designated paper information returns. The transmittal identifies the filer and gives the IRS a count of the enclosed returns plus the totals required for that type. The IRS’s covered returns are Forms 1097, 1098, 1099, 3921, 3922, 5498, and W-2G.
Each IRS Form 1099 carries one recipient’s information. You send the transmittal with those individual forms. It doesn’t replace them or report each recipient’s taxable income on its own.
If you received a 1099, you don’t need to prepare the sender’s summary. Filing the transmittal is the responsibility of the person or business submitting the paper returns.
Who must file Form 1096?
You generally must file Form 1096 if you’re an individual or business submitting a covered information return on paper, provided IRS rules allow you to file that way. The form’s instructions explain this filing requirement.
Check the payment against IRS reporting obligations before preparing a 1099. Not every business payment requires one. Paper 1099-NEC and 1099-MISC submissions need a transmittal. Being required to issue those returns doesn’t mean you’re allowed to mail them.
| Situation | Transmittal needed? | Why |
|---|---|---|
| You submit covered paper information returns | Yes, if paper filing is permitted | It accompanies the returns you're sending to the IRS. |
| You file those returns electronically | No | The electronic submission doesn't use a paper transmittal. |
| You only receive a 1099 | No | Receiving a statement doesn't make you the filer of the payer's returns. |
Your role matters here. Receiving a 1099 and issuing one are separate matters. Your business may have its own reporting duties regardless of statements you personally receive.
Do you need Form 1096 when filing electronically?
No. You don’t send Form 1096 with returns you e-file through an IRS-supported system. Count all your information returns together when checking whether e-filing is required. W-2s count, even though they go to the Social Security Administration.
A business with the following returns reaches the threshold.
| Return type | Number |
|---|---|
| Forms W-2 | 4 |
| Forms 1099-NEC | 3 |
| Forms 1099-MISC | 3 |
| Combined total | 10 |
That’s 10 returns altogether, so e-filing generally applies under the aggregate e-file rule. Having fewer than 10 of each type doesn’t avoid that requirement.
An approved hardship waiver can permit paper filing; see the waiver rules. Paper W-2s use Form W-3 as their transmittal to Social Security, rather than the summary used for paper 1099s.
To use the IRS’s free IRIS Taxpayer Portal for your 1099s, you’ll first need to complete enrollment and get a Transmitter Control Code (TCC). This code identifies your business when you e-file. Follow the enrollment instructions on the IRIS portal.
Where can you get official Form 1096?
For paper filing, order the scannable transmittal directly from the IRS. You can order official forms through its paper information-return ordering service. Allow time for delivery before your filing deadline; downloading a copy isn’t a substitute for receiving the paper original. If you choose an authorized electronic filing method instead, you won’t need this paper transmittal.
Do not mail the informational PDF: The version on IRS.gov looks like the official form, but printing it doesn’t produce an acceptable scannable filing copy. The official PDF notice states that you must not print and file that download. Some underlying information returns have exceptions allowing approved printable Copy A forms. Those exceptions don’t make the downloadable transmittal acceptable for paper filing.
What should you check before completing Form 1096?
- Start with your filing method. Count returns across types to confirm that IRS rules permit paper filing.
- Sort by form type. The IRS requires a separate transmittal for each type, including 1099-NEC and 1099-MISC.
- Look at who’s filing. Check that the same name, address, and taxpayer identification number appear on the transmittal and attached returns, not the recipient’s number. See the paper filing instructions.
- Count only completed returns for Box 3. Blank and voided forms don’t belong in the count.
- Check the returns against payment records, including federal income tax withheld for Box 4. Box 5 uses amounts specific to each return type. For unresolved differences, discuss record cleanup through bookkeeping services under a separate engagement.
How do you complete Form 1096?
Use your enclosed returns to fill in the filer fields on Form 1096. The name and identification number must match. Include the filer’s address and contact details before entering the group totals.
1. Which number belongs in Boxes 1 through 6?
| Box | Entry |
|---|---|
| 1 or 2 | Enter an employer identification number (EIN) in Box 1 or a Social Security number (SSN) in Box 2. Don't complete both. Sole proprietors use their EIN; those without one use their SSN. An individual outside a trade or business uses an SSN. |
| 3 | Count the correctly completed returns you're sending, not the sheets of paper. Exclude blank or voided returns and the transmittal. |
| 4 | Add the federal income tax withheld on the enclosed returns. |
| 5 | Use the total from the source boxes listed for that return type. |
| 6 | Put an X beside one return type only. |
The IRS box instructions explain these entries. Sign, date, and enter your title after checking the completed form.
2. How do you calculate Box 5?
Use the designated boxes across all returns in the group. The calculation depends on which form you’re sending:
| Return type | Source boxes for the total |
|---|---|
| 1099-NEC | 1 and 3 |
| 1099-MISC | 1, 2, 3, 5, 6, 8, 9, 10, and 11 |
| 1098-T, 1099-A, or 1099-G | Leave Box 5 blank |
Don’t total every dollar figure you see. For other forms, find the source boxes in the IRS’s form-specific list.
3. How many separate transmittals do you need?
One contractor doesn’t mean one transmittal. Under the transmittal rules, group returns by type. Your 1099-NEC returns share one summary, while 1099-MISC returns need another. Each summary generally covers all the contractors within that group.
When is Form 1096 due?
Look at the return attached to your transmittal to find the deadline. A paper 1099-NEC filing comes due earlier than most other covered paper returns. You submit the package in the year after the tax year it reports.
| Form group | Usual deadline | Tax year 2026 example (filed in 2027) |
|---|---|---|
| 1099-NEC | January 31 | February 1, 2027 |
| 1099-LPS | February 1 | February 1, 2027 |
| Most other covered paper returns | February 28 | March 1, 2027 |
| 5498 series | May 31 | June 1, 2027 |
If the deadline falls on a Saturday, Sunday, or applicable legal holiday – you have until the next business day to file. The table applies those adjustments to the official due dates for 2027.
Before mailing, check the information-return instructions for exceptions affecting the returns you’re submitting.
Sending recipients their statements is a separate obligation with its own timing. Don’t assume that furnishing a recipient copy completes the IRS filing, or that the IRS must process your submission by the filing deadline.
Where should you mail Form 1096?
Where you mail the package depends on your principal business location or your legal residence. For a Florida business, the 2026 instructions list:
Internal Revenue Service
P.O. Box 149213
Austin, TX 78714-9213
Check the IRS mailing table for your state’s destination. Use that destination rather than the payment or correspondence address on an unrelated IRS notice.
How should you package the forms?
- Include the signed transmittal.
- Enclose the corresponding Copy A returns. If a sheet contains two or three forms, send the whole sheet, even if some are blank or voided.
- Mail the forms flat, without folding them.
- Keep all forms free of staples.
The paper submission rules cover packaging requirements. Each group of returns should stay with the transmittal prepared for it.
What if Form 1096 or a paper information return is incorrect?
Before filing
If an unfiled information return contains an error, enter an X in its VOID checkbox and prepare a replacement with the correct information. Use the replacement’s figures on your transmittal. Don’t mark CORRECTED for a return you haven’t submitted.
After filing
For an error discovered after paper filing, generally submit a corrected Copy A with a transmittal. Provide a corrected recipient statement where it’s required. The correction instructions explain which steps apply. The IRS generally doesn’t require you to correct the previously filed transmittal itself.
Originals and corrections can share a transmittal when they’re the same return type. A requirement to e-file the originals generally carries over to any corrections you submit.
The error determines how you correct the return. An amount, a recipient’s name, and a taxpayer identification number can call for different procedures, sometimes requiring two returns for correction.
Paper filing despite an e-filing requirement can bring penalties, as can late returns or incorrect information. You’ll find the rules for filing errors in the IRS penalty guidance.
When should you get professional help with information returns?
Before filing, get help tracing any unexplained difference between payment records and returns. A professional can compare name and taxpayer identification number differences against your records. You can request a review of whether the electronic filing requirement applies to you. If contractor payments involve several return types, ask about separately scoped reporting help through H&S Accounting & Tax Services’ payroll services.
Already filed something incorrect? Bring copies of the submitted returns alongside the payment records so a professional can assess the correction needed. Agree on the work before it starts. Preparing returns, correcting prior filings, and representing you before the IRS aren’t automatically included together in your engagement.
Frequently asked questions
How do Form 1096 and Form 1099 differ?
Each 1099 identifies a recipient and reports specific amounts. The transmittal gives the IRS a summary of the paper returns enclosed. The enclosed returns supply the details for each recipient.
Does mailing just one Form 1099 require you to include a transmittal?
Yes, provided you’re permitted to file on paper. The transmittal requirement generally applies even when your package contains a single qualifying return. Count your other information returns when checking whether e-filing is required.
Can you send a transmittal without filing a 1099?
You can use it with other covered paper returns, such as designated 1098 or 5498 forms. There must be returns to transmit; the summary isn’t an information return you submit on its own.
Do Forms W-2 use Form W-3 instead?
Paper W-2 Copy A forms go to the Social Security Administration with W-3. The W-3 instructions cover this submission. Your W-2 count matters when checking the combined electronic filing requirement.
What should you do about a late paper information return?
File the return correctly without further delay. Filing penalties depend on your circumstances, submitting the missing return doesn’t automatically qualify you for relief. The IRS may still assess a penalty.
Does each contractor's return need its own separate transmittal?
No. The return type determines the group. Contractors’ returns of the same type can share one transmittal; two different return types for one contractor require separate transmittals.
Check your Form 1096 and paper returns before mailing
Set the completed transmittal beside the Copy A returns you’re sending, then check the entries against that group.
- Confirm you’re allowed to file on paper. An electronic submission doesn’t need a duplicate paper package.
- Use official forms or acceptable substitutes that meet IRS specifications. The downloadable informational Form 1096 PDF is not an acceptable filing copy.
- Recount the completed returns for Box 3, not the sheets. Add their federal withholding for Box 4; use the amounts designated for that return type in Box 5, where applicable.
- Compare the enclosed return type with your Box 6 selection. Keep different types under separate transmittals.
- Sign the transmittal and verify the deadline and state-specific address in the final IRS instructions.
For records you can’t reconcile or filing requirements you haven’t resolved, request a review.